Discover the right business loan in Australia. Compare options and get the funding your business actually needs.

Your business does not have to fit a category to be funded. If yours is not listed, it is still worth asking.
Put your best foot forward by preparing strong answers to 9 questions a lender might ask you.
Put your best foot forward by preparing strong answers to 9 questions a lender might ask you.
B2B embedded finance isn’t just a tech upgrade; it’s a strategic lever to boost acquisition, conversion, and retention.
Your existing clients aren’t just customers; they’re a source of potential growth.
Business van loans for Australian SMEs
Keep your vans running and your schedule full, with financing that keeps pace.
About
What is a business van loan?
A business van loan helps you buy a commercial vehicle, whether that's a compact delivery van, a high-roof transporter or a refrigerated unit, while spreading the cost over time.
Most Australian business owners opt for a chattel mortgage, where you take ownership of the van immediately, and the lender secures the loan against the vehicle itself.
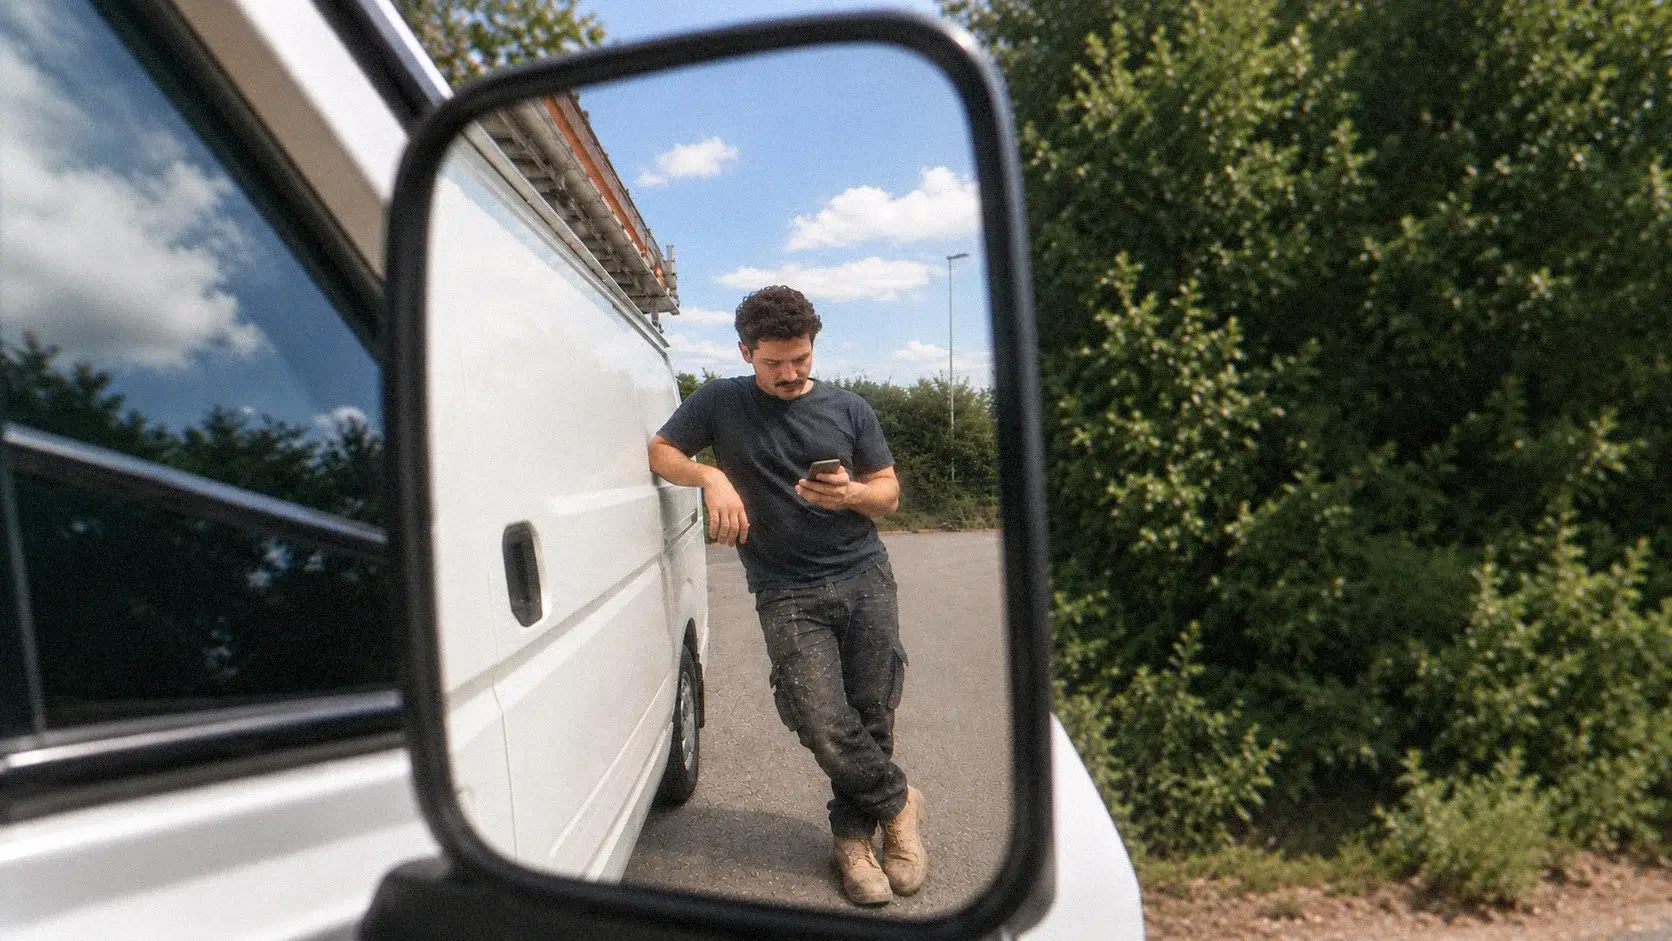
Ways to use a business van loan
- Adding a van to keep up with a busy delivery or service schedule
- Replacing an ageing van to cut down on breakdowns
- Financing a refrigerated van or mobile workshop
- Building out a fleet one van at a time
Eligibility
You may be eligible for a business van loan if your business:
- Has been trading for 6–12 months or more
- Has a mostly clean credit history (past credit issues are considered case by case)
- Has an active ABN or ACN and operates in Australia
Criteria vary between lenders, and the lender makes the final call.
Why it works
What are the benefits of getting a business van loan?
Preserve working capital
Keep your cash reserves for day-to-day operations, marketing or emergency repairs.
Potential tax perks
You may be able to claim tax deductions for interest charges and vehicle depreciation.

Immediate ownership
With a chattel mortgage, you own the asset from day one, allowing you to claim GST upfront.
Flexible repayments
Tailor your loan term and include an optional balloon payment to lower your monthly costs.
Is a business van loan right for you?
It suits many businesses, but it's worth weighing up the trade-offs first.
Ask yourself
- If I choose a balloon payment, do I have a plan for the lump sum due at the end?
- If I fell behind on repayments, could my business absorb losing the van?
- Have I compared the total interest cost of a longer term or balloon against a shorter loan?
Potential drawbacks
- If you opt for a balloon payment to lower your monthly costs, a large lump sum will be due at the end of the loan.
- The loan is secured by the van, so the lender can take it if you fall behind on payments.
- A longer term or balloon payment will increase the total interest you pay over the life of the loan.
Nothing ticked yet. Tick a question and the drawback it bears on is marked opposite.
Nothing is stored, sent or assessed. This only marks what to raise.
Business van loans
Key features
- Loan amount
- From $5,000. Maximum varies by asset and business profile
- Term
- 1 – 7 years
Getting started
How to apply for a business van loan
Step 1: Get a quote
Tell us what your business needs and get quotes from 95+ bank and non-bank lenders.
Step 2: Get approved
Confirm your quote and we'll manage the application with your lender, so you can focus on running your business.
Step 3: Get funded
Sign your finance documentation and receive funding. It is that simple.
Awarded and sorted
Awards & key milestones
Our milestones are a testament to the amazing people behind Valiant.
Our panel
95+ business lenders
in your back pocket
- All lenders
- Equipment
- Vehicle
- Working capital
- Invoice
- Trade & supply chain
- Commercial property
- Construction


Why Valiant
Just one simple application.
Let us do the heavy lifting, comparing the panel and negotiating. You get all the options side by side and choose the one that’s right for you.
Dedicated specialists by your side.
You get a personal specialist who knows which lenders suit your industry and how to structure a deal so it actually works for you.
Your credit score, protected.
Explore with no credit check. See all your options, compare them properly, and choose with confidence.
30,000+ SMEs we've worked with.
Construction, hospitality, manufacturing, healthcare. Whatever your business needs, we know how to get it funded with the right loan.
Related articles
View all
FAQs
What happens if I can’t make a repayment?
Since the van acts as security for the loan, lenders do have the right to repossess it if payments stop. That said, it’s a last resort and lenders much prefer to work with you to find a solution first.
Do I need to be GST registered to get a business van loan?
Not always, but being GST registered can make it easier to claim the GST on the purchase price back from the ATO.
Can I get a van loan if I'm a new startup?
Yes. It can be a bit more of a climb for new startups, since lenders usually require at least 6-12 months of trading. However, some specialist lenders offer low-doc loans for new ABN holders. Keep in mind, you may need a larger deposit.
Is the interest tax-deductible?
Generally, yes. If the van is used for business, you can typically claim the interest component of the repayments, as well as the depreciation.
Do I need a deposit for a business van loan?
Not always. Many lenders offer 100% finance, meaning you can drive away without an upfront cash deposit, though providing one can lower your interest costs.
Can I buy a used van from a private seller?
Yes, but some lenders prefer dealership sales. For private sales, they may request an independent inspection or valuation.
Can I buy a used van with a business loan?
Yes, you absolutely can. Most lenders are happy to finance used vans, as long as they aren't hitting their 'retirement age' (usually 10–15 years) by the time the loan wraps up.