Discover the right business loan in Australia. Compare options and get the funding your business actually needs.

Your business does not have to fit a category to be funded. If yours is not listed, it is still worth asking.
Put your best foot forward by preparing strong answers to 9 questions a lender might ask you.
Put your best foot forward by preparing strong answers to 9 questions a lender might ask you.
B2B embedded finance isn’t just a tech upgrade; it’s a strategic lever to boost acquisition, conversion, and retention.
Your existing clients aren’t just customers; they’re a source of potential growth.
Business ute loans for Australian SMEs
Get the ute that earns its keep and pay it off as the work comes in.
About
What is a business ute loan?
Business ute loans let you buy or upgrade a ute for your operations. You repay it in instalments over an agreed term, rather than having to pay it all upfront. Ute loans can cover:
- Standard utes
- Dual cab utes
- 4x4 utes
- Tray-back utes
- Utility vehicles with towing capability
- Specialised work utes
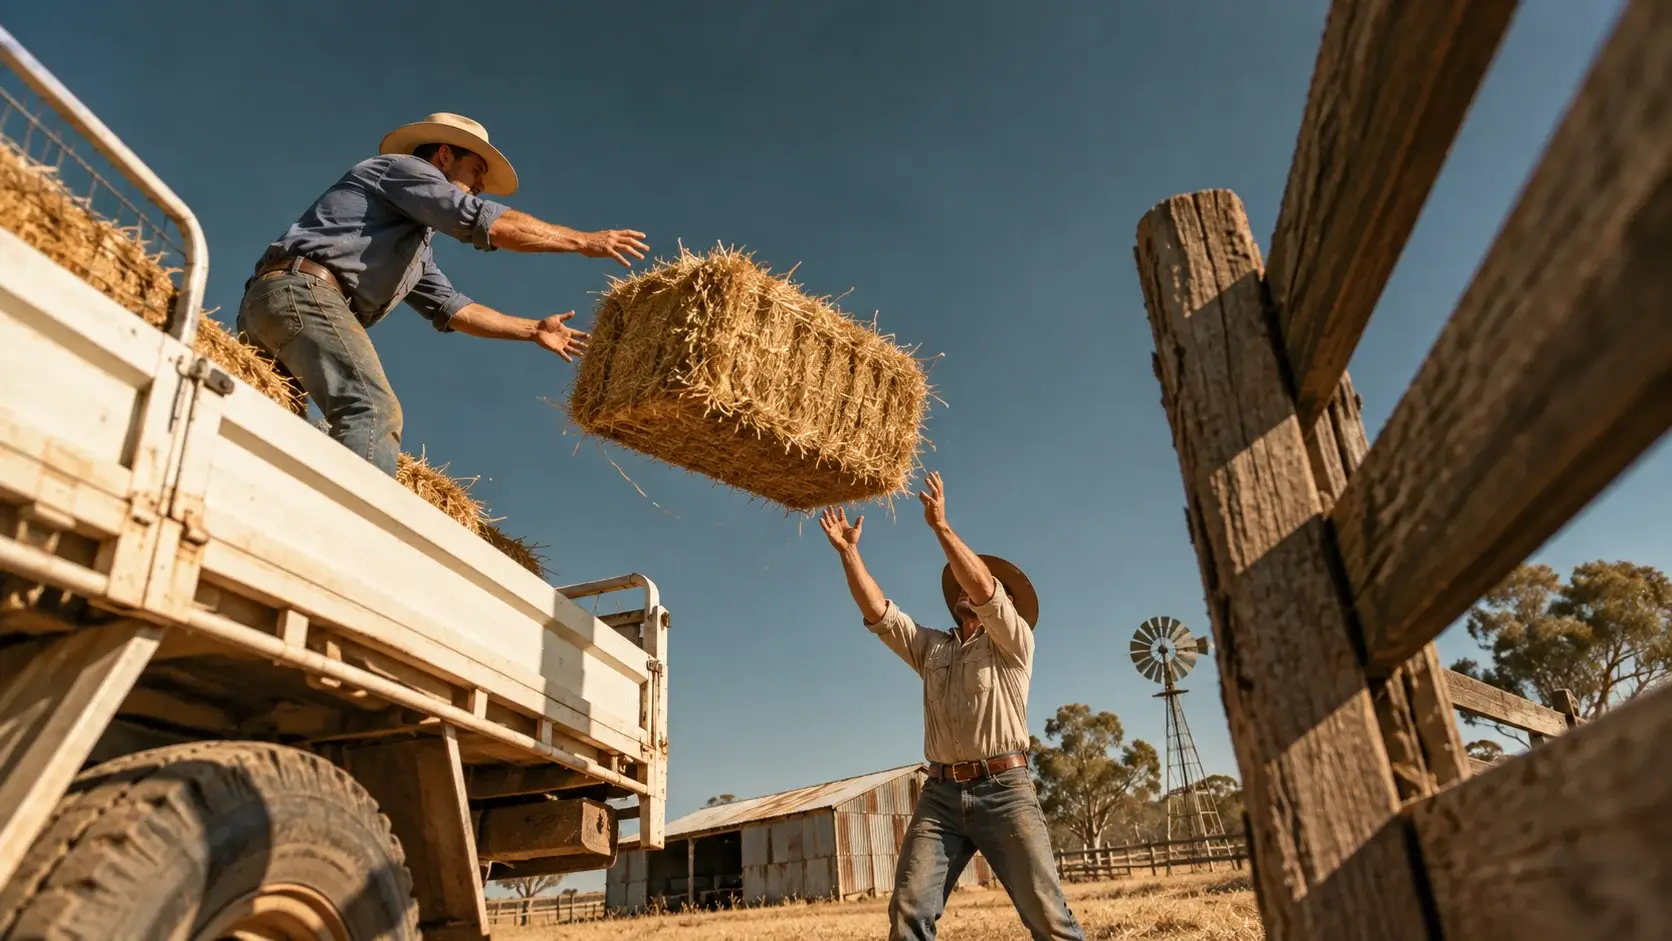
Ways to use a business ute loan
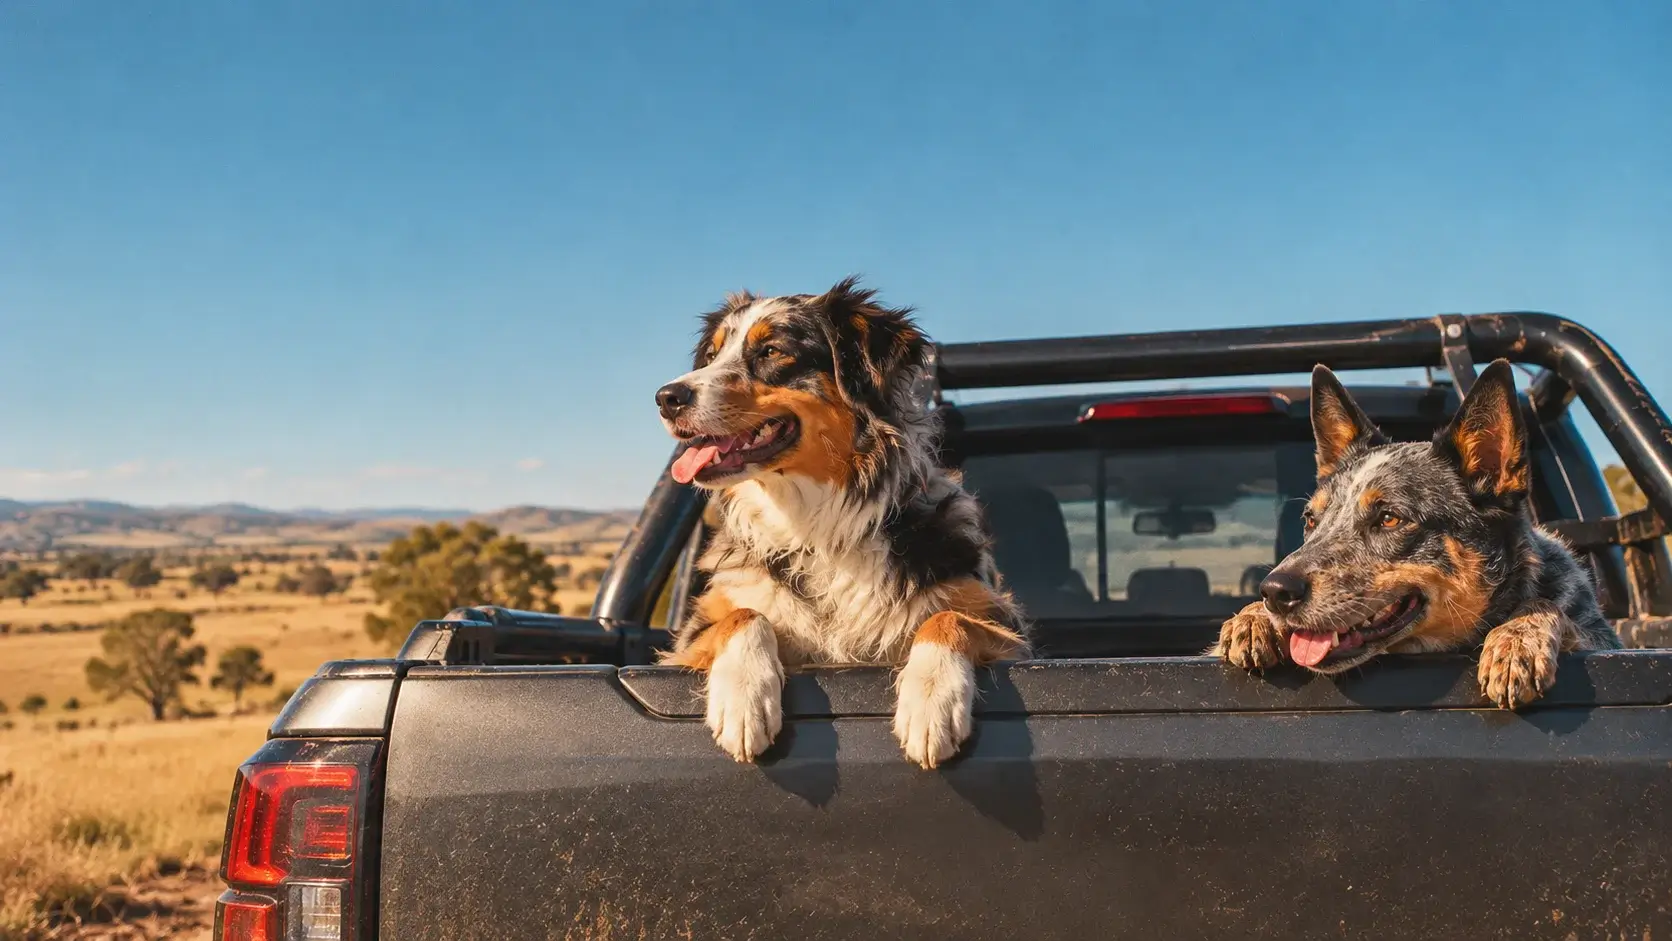
- Replacing a ute that's becoming unreliable or costly to maintain
- Adding a ute so new hires or extra jobs aren't held up
- Financing a 4x4, tray-back or towing-capable ute for a specific job
- Building out a fleet one ute at a time
Eligibility
Lenders typically consider things like:
- Business financial health
- Cash flow stability and ability to make repayments
- Credit history
- Ute make, model, age, and condition
- How the ute will be used in the business
Why it works
What are the benefits of getting a business ute loan?
Carry more gear and tools
Utes often have higher payload capacity so you can transport large or awkwardly shaped items safely.
Customisable for your trade
Utes can be fitted with trays, toolboxes, towing gear or other trade-specific modifications.
Access a newer, better-equipped ute
Financing lets you get a current-model ute with better safety and tech than cheaper, older vehicles.
Potential tax advantages
Ute depreciation, running costs and the interest portion of your loan may be tax-deductible.
Cash flow flexibility
Paying for your ute over time frees up cash for daily operations, growth or unexpected expenses.
Is a business ute loan right for you?
It suits many businesses, but it's worth weighing up the trade-offs first.
Ask yourself
- Could heavy use mean the ute is worth less than expected when I want to sell or trade it in?
- Do I have specific modification plans, and would a standard loan agreement allow them?
- Have I checked how using the ute for work will affect my insurance premium?
Potential drawbacks
- High mileage, heavy loads or off-road use can make utes depreciate faster.
- Some loans restrict trade or farm modifications, which could also affect insurance.
- Carrying heavy equipment may raise your insurance premiums.
Nothing ticked yet. Tick a question and the drawback it bears on is marked opposite.
Nothing is stored, sent or assessed. This only marks what to raise.
Business ute loans
Key features
- Loan amount
- From $5,000. Maximum varies by asset and business profile
- Term
- 1 – 7 years
Getting started
How to apply for a business ute loan
Step 1: Get a quote
Tell us what your business needs and get quotes from 95+ bank and non-bank lenders.
Step 2: Get approved
Confirm your quote and we'll manage the application with your lender, so you can focus on running your business.
Step 3: Get funded
Sign your finance documentation and receive funding. It is that simple.
Awarded and sorted
Awards & key milestones
Our milestones are a testament to the amazing people behind Valiant.
Our panel
95+ business lenders
in your back pocket
- All lenders
- Equipment
- Vehicle
- Working capital
- Invoice
- Trade & supply chain
- Commercial property
- Construction


Why Valiant
Just one simple application.
Let us do the heavy lifting, comparing the panel and negotiating. You get all the options side by side and choose the one that’s right for you.
Dedicated specialists by your side.
You get a personal specialist who knows which lenders suit your industry and how to structure a deal so it actually works for you.
Your credit score, protected.
Explore with no credit check. See all your options, compare them properly, and choose with confidence.
30,000+ SMEs we've worked with.
Construction, hospitality, manufacturing, healthcare. Whatever your business needs, we know how to get it funded with the right loan.
Related articles
View all

FAQs
Are there any restrictions on how I use the ute?
Financed utes need to be used primarily for business purposes. This is generally more than 50% of the time, according to the ATO. Some loans may also have conditions on things like off-road driving, towing, or modifications, so check your agreement to make sure it suits your operations.
How much deposit do I need for a business ute loan?
You don't always need a deposit for a business ute loan, but contributing 10-20% can help reduce your loan amount and total interest. Factors like your business's financial health, credit history, and loan amount will determine whether or not a deposit is required.
Can I upgrade or trade in my ute before the loan ends?
Yes, it's possible to upgrade or trade in vehicles mid-loan, including utes. However, early payout fees may apply, and you often have to settle the remaining balance of your loan before you can upgrade.
Can I include modifications or accessories in the ute loan?
Business ute loans often cover essential business-related modifications and accessories, like tool drawers, roof racks, and tow bars. Always check your loan agreement to confirm what applies in your case.
Can I finance new and used utes?
Yes, a ute loan lets you finance both new and used vehicles. Remember to weigh in the pros and cons of each option. For example, financing a new ute often comes with better terms, like lower interest rates, but is overall pricier. On the other hand, used utes require a lower principal loan amount but may come with stricter loan terms.